
Your contingent cargo policy covers up to $1 million per occurrence. How many of your active clients have inventory in the same facility right now?
If the answer is four or more, you have already outgrown what that limit was designed to handle.
Third-party logistics providers carry a risk structure that commercial insurance was not built to price correctly. Standard contingent cargo coverage treats each loss as a discrete event. Third-party logistics operations do not experience risk that way. One fire in one warehouse is not one claim. It is as many claims as you have active clients with inventory on those shelves. One computer system failure does not interrupt one relationship. It interrupts every client whose shipment was moving through your transportation management system at that moment.
Here is what matters before we get into the specifics: the commercial market prices third-party logistics risk as a category, not as an individual operation. If you have a strong safety culture, clean loss history, and well-structured client contracts, you are subsidizing the operators who do not. Here is how a captive changes that in plain terms: instead of paying premiums to a commercial carrier and watching them disappear permanently, you pay premiums into a licensed insurance company that your business owns. Claims still get paid. But when a year runs clean, the premium you paid stays in your company rather than building a carrier's investment portfolio. The surplus from your underwriting performance accumulates in an entity you control. This article explains the specific gaps in standard third-party logistics coverage, what a captive covers differently, and what it costs to run the structure.
Why Third-Party Logistics Risk Compounds Differently
There are three things that make a third-party logistics operation structurally different from a carrier or a warehouse-only operator, and all three affect how claims aggregate.
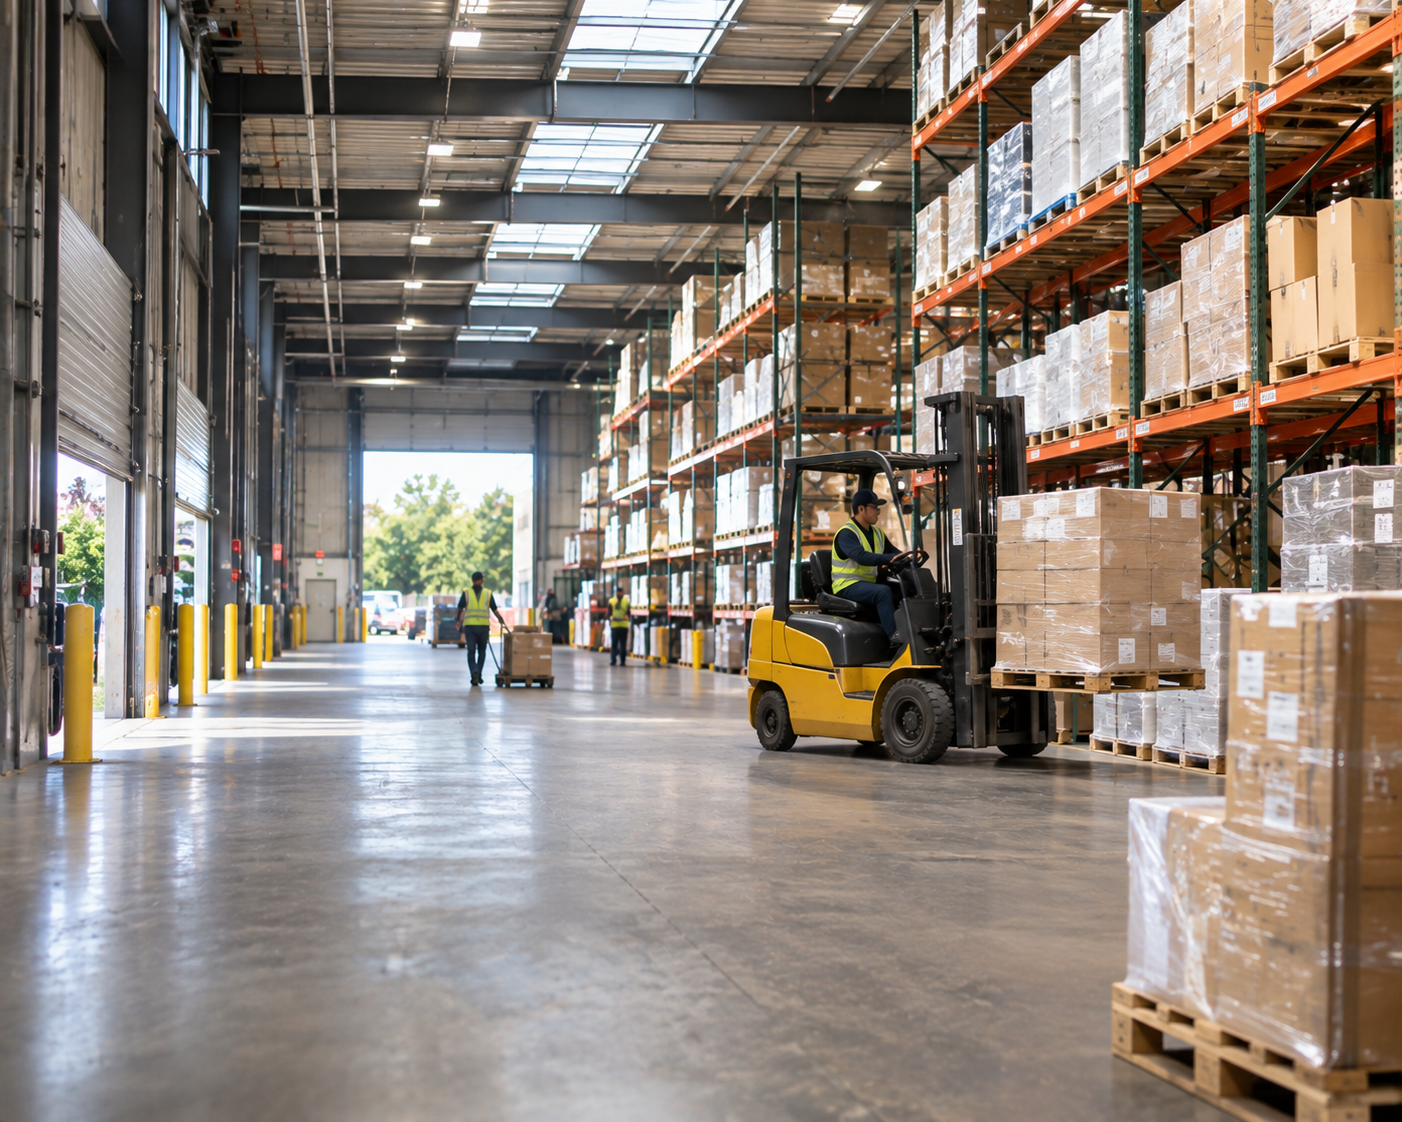
The first is multi-client occupancy. A carrier owns the freight and runs one set of risk relationships. A warehouse-only operator knows exactly who owns what on its shelves and can price accordingly. A third-party logistics provider is simultaneously responsible to multiple clients, often with inventory from several of them in the same physical facility at the same time. When something goes wrong in that facility, it does not go wrong for one client. It goes wrong for all of them. Standard contingent cargo policies cover up to a specified per-occurrence limit across all claims arising from a single incident. At $1 million per occurrence, a loss event that damages inventory across six active client accounts leaves each client sharing that limit, which works out to roughly $166,000 each before coverage runs out, regardless of what each account actually lost.
The second is contractual liability exposure. Third-party logistics providers routinely sign contracts with both carriers and clients that contain indemnification and hold-harmless clauses. When a carrier causes a loss but the third-party logistics provider signed a contract that accepted liability for cargo in that carrier's possession, the claim flows back to you. Standard commercial general liability policies contain explicit exclusions for liability assumed under contract. The contingent cargo policy your operation carries may not cover losses that traveled back to you through a contract with a carrier. That exposure sits in the gap between two policies, and most third-party logistics operators do not discover it until they are filing a claim.
The third is technology dependency. A modern third-party logistics operation runs on a transportation management system. That system tracks every shipment, communicates with clients, coordinates carrier assignments, and handles billing. When it fails, through a software fault, a cyber event, or a vendor outage, the failure cascades across every active client relationship simultaneously. The errors and omissions coverage most third-party logistics providers carry was designed to respond to negligent acts: a routing error, a carrier selection mistake, an incorrect freight document. It was not designed to respond to a system failure that caused the error. That distinction matters in a claim, and it usually resolves in the carrier's favor.
Put those three things together and what you have is a risk structure where a single incident can trigger liability to multiple clients simultaneously, where the legal path of that liability can travel through contracts that standard policies exclude, and where the technology failure that caused the operational breakdown is not covered by the professional coverage the operator carries. The commercial insurance market has a package solution for this. It just was not designed to handle all three exposures at once.
Where the Standard Policy Ends
Third-party logistics operators typically carry a package that looks complete on paper: contingent cargo, commercial general liability, errors and omissions, workers' compensation, and commercial auto if the operation owns vehicles. The package contains gaps that show up clearly in the fine print, and they are not gaps that most operators discover in the coverage review before a loss.
Contingent cargo sublimits.
Standard contingent cargo insurance was designed for a simple scenario: your client's goods are in transit, the carrier's insurance comes up short, and your policy fills the gap for that one shipment. The policy limit applies to that one event involving that one client. That is not how loss events work in a multi-client warehouse. When a fire damages inventory belonging to six different clients stored in the same building, all six claims hit the same per-occurrence limit at once. The limit was never set with that scenario in mind. A third-party logistics operator with $8 million in active client inventory across a single facility and a $1 million per-occurrence contingent cargo policy has $7 million in uninsured exposure before the first claim is filed.
Contract liability exclusion.
The commercial general liability form contains what carriers call the contractual liability exclusion, which removes coverage for liability assumed under contract. That exclusion applies to a wide range of contract language that third-party logistics providers sign routinely: warehouseman agreements that accept strict liability for client inventory, carrier contracts that acknowledge the third-party logistics provider as the responsible shipper, and client agreements that hold the provider liable for consequential damages if shipments are delayed or misdirected. When a loss occurs and the claim traces back to a contractual obligation your operation accepted, the commercial general liability carrier applies the exclusion and your operation is left with an obligation that nothing covers.
Defense costs within the errors and omissions limit.
Errors and omissions policies in the third-party logistics space are frequently written with defense costs inside the policy limit rather than in addition to it. Take a claim with $400,000 in defense fees and $900,000 in settlement demand. Against a $1 million limit with defense inside, the carrier pays $400,000 to defend and $600,000 toward the settlement. The remaining $300,000 of the settlement comes out of your operation's pocket. The policy that looked like $1 million in coverage delivered $600,000 in actual settlement protection. That is not an edge case. It is the default policy structure for most third-party logistics errors and omissions forms.
The commercial market's response to these gaps is not to fix them. It is to sell additional endorsements that partially address them at additional premium, or to offer higher limits at pricing that reflects the category's overall loss experience rather than the individual operator's. For a third-party logistics provider with strong safety practices and clean loss history, those options mean paying more to cover risks you manage well, and still leaving the structural gaps in place.
Commercial insurers also do something third-party logistics operators rarely think about: they invest the premiums they collect. The float, the period between when a premium is paid and when a claim is settled, generates investment income. That income belongs to the carrier. For a third-party logistics operator paying $350,000 a year across its commercial lines, the float the carrier holds on those premiums at any given time is generating income that your operation never sees. A captive changes that.
What a Captive Covers That Commercial Markets Will Not
A captive insurance structure gives a third-party logistics operation access to coverage forms that commercial carriers will not write and policy limits that reflect the actual risk profile of the operation rather than the assumed risk profile of the category.
Multi-client aggregation coverage. A captive can write a policy with per-occurrence limits sized to the actual aggregate inventory exposure in each facility, not to what the commercial market is willing to offer. If a third-party logistics operation maintains an average of $8 million in active client inventory in a single building, the captive can hold a policy limit sized to that exposure. The commercial market sets limits based on what the category will bear. A captive sets limits based on what the operation actually needs. When a loss hits multiple clients simultaneously, the captive responds to the aggregate exposure, not to a limit that was designed for a single-client loss event.
Contract liability coverage. A captive can write coverage that explicitly responds to liability assumed under contract, acknowledging the actual contract language a third-party logistics provider signs with carriers and clients. The commercial market excludes contract liability because the carrier cannot price it at the level of the individual operator. A captive can, because the captive's underwriting data is the operator's own loss history and contract portfolio, not the category average. When a claim travels through a hold-harmless clause back to the third-party logistics provider, the captive policy responds to it.
Technology failure coverage. A captive can write an errors and omissions form that covers technology system failures as a first-class event rather than requiring the failure to be tied to a specific negligent act. If a transportation management system outage causes a cascade of misdirected shipments and delivery failures, the captive policy responds to the system failure. That is a coverage gap in every standard errors and omissions form in the market, and it is a gap that matters more as third-party logistics operations become more technology-dependent.
Defense costs outside the limit. A captive-written errors and omissions policy can be structured with defense costs in addition to the policy limit rather than within it. For a third-party logistics operation facing the kind of multi-client claims that come from a significant loss event, that structure changes the effective coverage dramatically. A $1 million limit with defense outside means $1 million available to settle claims after spending what is needed to defend them. A $1 million limit with defense inside can be exhausted by a heavily contested claim before any settlement is reached.
The captive does not replace the commercial market across every coverage line. The commercial market remains the right structure for high-severity, low-frequency risks: catastrophic liability, major property damage, workers' compensation tail claims. What a captive adds is a coverage layer for the mid-range, predictable exposures that the commercial market prices inefficiently because it cannot distinguish your operation from the rest of the category. It can also write coverage for risks the commercial market does not insure at all, including certain contractual obligations that standard forms explicitly exclude.
The risk pool structure works as follows: when a loss occurs, your captive pays a defined share of that loss and the pool of which your captive is a member pays the remainder. Surplus from years when claims come in below what was funded stays in your captive. It accumulates as a financial asset your operation owns, available as reserves, available for investment, and available to your business in ways that a commercial premium payment is not. A premium paid to a commercial carrier is gone when you pay it. A premium paid into your captive is not.
The Economics and the Tax Treatment
The financial case for a captive insurance structure starts with one observation: the commercial insurance market prices your operation using averages. If your loss history is better than the category average, you are paying a premium that reflects losses you are not having. The captive recaptures that premium as underwriting income.
Here is what that looks like at scale. A third-party logistics operation paying $300,000 a year in contingent cargo and errors and omissions premiums to commercial carriers typically generates an overall combined ratio in the 60 to 70 percent range on those lines if it maintains clean loss controls, careful contract management, and consistent carrier oversight. At a 65 percent combined ratio, $300,000 in annual premium produces roughly $105,000 in underwriting profit and investment income that flows to the carrier's shareholders instead of your operation. Over five years, that is $525,000 in economic value that left the building. In a captive, that value stays.
That math does not require perfect loss history. It requires loss history that is better than what the commercial market assumes for the category. For a third-party logistics operation that actively manages risk: written client contracts, formal freight claims procedures, monitored carrier performance, structured technology backup protocols. The gap between actual performance and market assumption is typically significant. The commercial market is pricing the whole category. Your operation is not the whole category.
The captive also retains float. Premiums paid into the captive are invested before claims are paid. For a captive funded at $300,000 per year, the investable float at the end of year three generates investment income at current rates that belongs to the captive's owner rather than to a carrier's investment portfolio. Over a ten-year horizon, the compounding effect of retained underwriting profit and retained investment income is what moves a captive from a coverage tool to a meaningful balance sheet asset.
On the tax side, a captive structured under Section 831(b) of the Internal Revenue Code can elect to be taxed only on investment income rather than on underwriting income, provided annual written premium stays at or below $2.9 million, which is the 2026 annual limit under that section. For qualifying captives, that means the premium paid to the captive is deductible as a business expense for the parent company, and the underwriting income accumulated in the captive is not taxed as it accrues. Only the investment income the captive earns is subject to tax at the standard corporate rate.
That tax treatment is legitimate when the captive is structured correctly around real insurance activity: genuine policies that transfer real risk, actuarially supported premiums, coverage that responds to actual claims, and a captive that functions as an operating insurance company rather than a tax-planning vehicle. The Internal Revenue Service can scrutinize captive arrangements and has designated several specific structures as listed transactions that carry significant penalty risk. A well-structured captive built around underwriting real risk avoids all of those. The tax benefit follows naturally from operating a legitimate insurance company. It is not the reason to form the captive. The reason to form the captive is to keep what your operation earns from managing risk better than the market assumes.
Who Qualifies
The conversation is worth having if several of these sound familiar:
- You operate a third-party logistics business with $250,000 or more in annual commercial insurance premiums. That is 3F's rule-of-thumb floor for logistics operations, consistent with the general standard for captive structures. At that premium volume, the economics of retaining underwriting profit and investment income within the captive are compelling.
- You have active inventory from multiple clients in shared facilities, and you are not certain your per-occurrence contingent cargo limit is sized to cover simultaneous claims across all of those accounts.
- You sign hold-harmless or indemnification clauses with carriers or shippers as a standard part of your contract process, and you have never reviewed whether the resulting liability is covered by any of your existing commercial policies.
- You run a transportation management system or other technology platform that your clients depend on for visibility and shipment coordination, and you are not certain your errors and omissions coverage responds to a system failure rather than only to negligent acts.
- You have experienced a cargo loss, a freight liability dispute, or a coverage dispute with a commercial carrier, and the experience revealed gaps you did not know existed before the claim was filed.
- You want the premiums that do not become claims to build your operation's financial reserves instead of building a carrier's underwriting profit.
If a few of those apply, a coverage review is the right starting point. We review the policies, identify the gaps specific to your operation's risk profile and contract structure, and tell you plainly whether a captive structure makes economic sense. If the math does not work yet, you leave knowing exactly what your program covers and where it falls short. The financial modeling, the premium levels, projected underwriting results, and reserve requirements, belongs to the paid feasibility study.
Third-party logistics insurance in the commercial market was designed for a simpler version of the business. Single-client relationships, straightforward cargo liability, and clean carrier contracts were the assumed risk profile when those policy forms were written. Modern third-party logistics operations run multi-client facilities, sign complex contract chains, and depend on technology platforms that did not exist when the standard contingent cargo form was drafted. The coverage needs to match the operation. 3F Captive Services works with third-party logistics operators who want their insurance premiums to build their balance sheet instead of a carrier's. Start at 3fcaptiveservices.com.
Sources
[1] Champion Risk & Insurance Services. The Complete Guide to 3PL Insurance for Transportation & Logistics. https://www.championrisk.com/3pl-insurance-guide
[2] FBD Groups. U.S. 3PL Insurance Guide: 7 Cargo & Liability Coverages. September 30, 2026. https://www.fbdgroups.com/post/is-your-3pl-insurance
[3] Zurich U.S. Warehousing and Logistics Captive Program. Captive insurance program requirements and highlights for warehousing and logistics companies. https://www.zurichna.com
[4] Roanoke Insurance Group. 3PL / 4PL Transportation and Logistics Insurance Coverages. https://www.roanokegroup.com
[5] Internal Revenue Code Section 831(b). Internal Revenue Service regulations on micro-captive insurance structures. 2026 annual premium limit: $2.9 million. https://www.irs.gov
Discover Tailored Insurance Solutions
Unlock the potential of customized captive insurance designed specifically for your unique business needs.