Don't burn cash on insurance
Cultivate your own coverage
While traditional carriers keep cannabis businesses in a holding pattern, a captive insurance company built for you by 3F Captive Services lets you harvest the underwriting profits, and design coverage that actually protects your operation.
The Traditional Market Leaves You Exposed
Licensed cannabis operations face a market failure: traditional carriers avoid the industry, forcing even the most scrupulous and regulation-abiding operators into a surplus market with sky-high premiums and coverage so thin it barely passes inspection.
The Cost of Prohibition-Era Insurance:
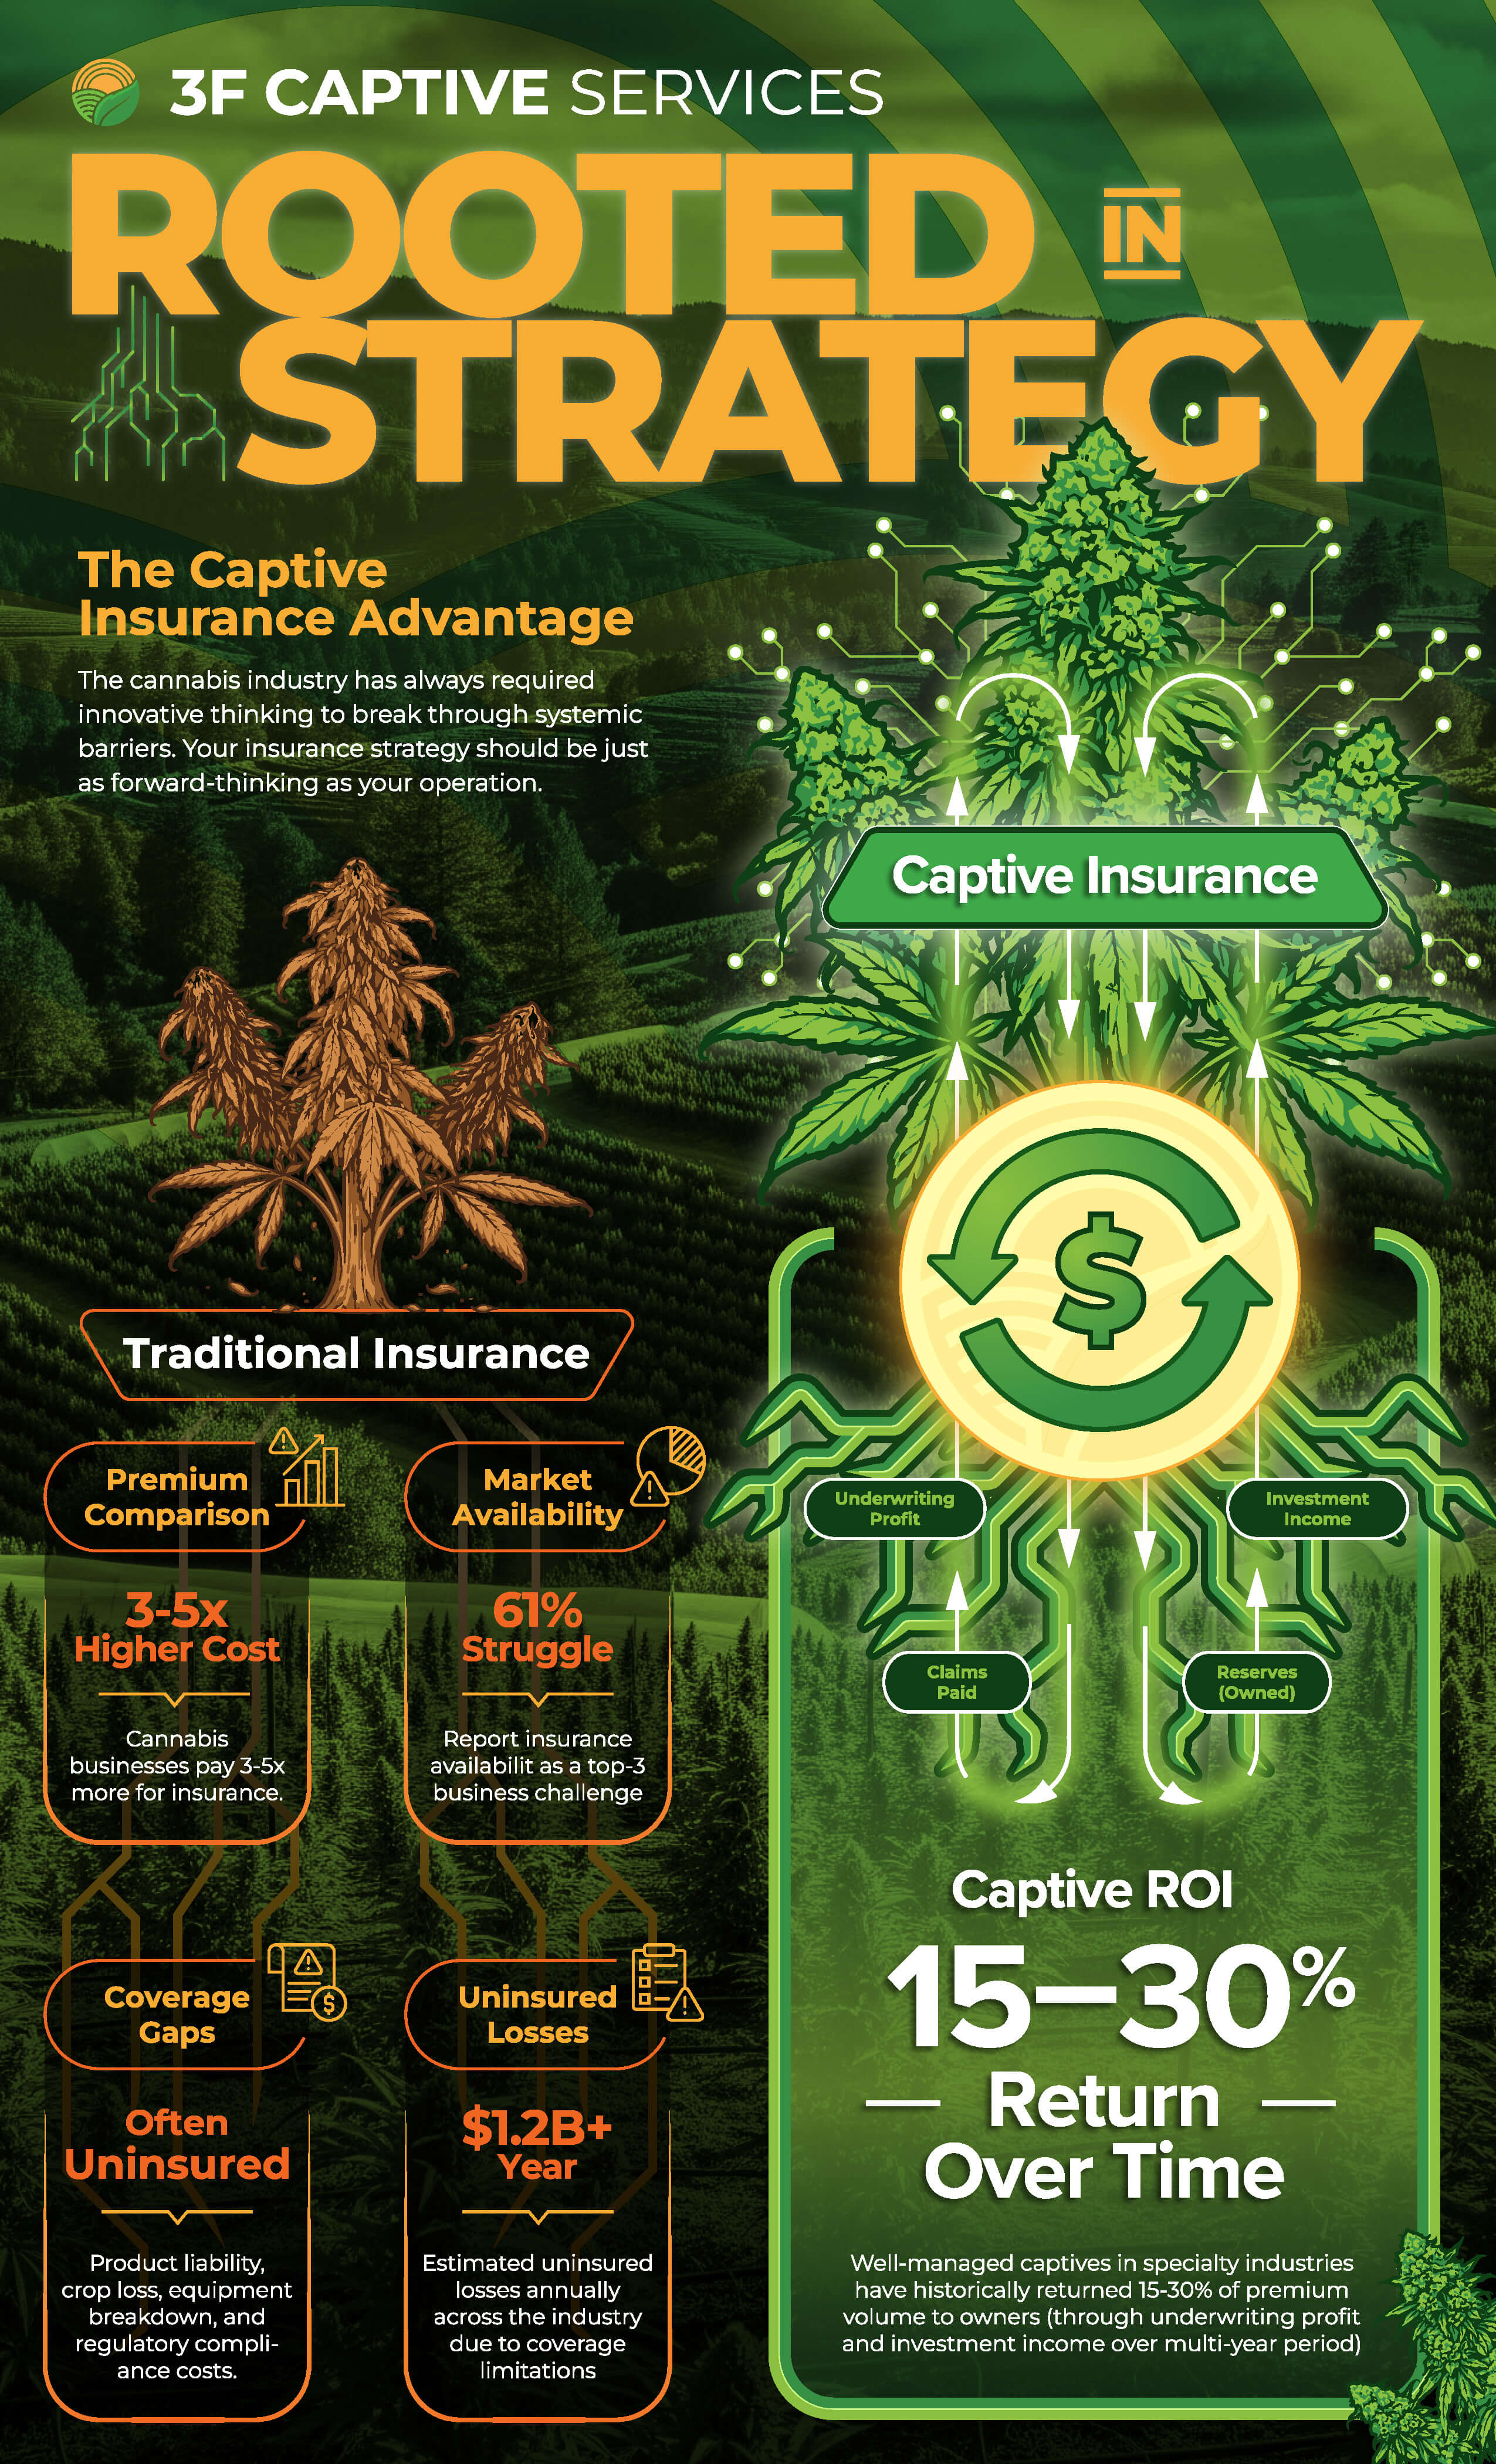
- Premium inflation: Cannabis businesses pay 3-5x more than comparable agricultural and retail operations
- Sparse carrier appetite: Federal classification keeps the majority of insurers on the sidelines, resulting in monopolistic pricing that hits operators where it hurts
- Critical gaps: Product liability, crop loss, equipment breakdown, regulatory defense, and many other risks are often completely uninsured
- Margin compression: High premiums compound the burden of elevated taxes and compliance costs
You're already cultivating excellence in operations. Why let insurance crush your profits?
What If Insurance Grew Profits Instead?
Captive insurance flips the traditional model in your favor. Instead of paying premiums to carriers who pocket underwriting profits and may dispute your claims, 3F Captive Services can help you form your own insurance company, allowing you to keep the profits of your business operations AND the profits of your insurance company.
From Cost Center to Profit Center:
Traditional insurance extracts capital from your business. A captive recirculates and grows capital while greatly expanding coverage into areas and for risks most operators don’t even realize are possible.
- Harvest underwriting profits when claims run lower than premiums
- Cultivate custom coverage designed for your actual risk profile
- Grow reserves that remain your asset, not someone else's balance sheet
- Access institutional reinsurance for catastrophic protection
The Yield:
Well-managed captives in specialty industries have historically returned 15-30% of premium volume to owners through underwriting profit and investment income over multi-year periods. Your disciplined risk management directly feeds your bottom line.
Plant Your Own Safety Net
How Captives Work
A captive is a strategic financial structure that turns your insurance program into an asset.
Three Branches of Protection:
Coverage That Actually Grows With You
Design policies addressing your real exposures: product liability for edibles and concentrates, crop failure for cultivation, equipment breakdown for extraction systems, regulatory defense costs, employment practices. You tell us the risk and work with us to design the policy that addresses your needs.

Your Risk Management Pays Dividends
Strengthened protocols and compliance programs benefit your organization and bottom line. With a captive, every claim you prevent through operational excellence stays in your ecosystem, not in an insurer's pocket.
Long-Term Root Strength
Build reserves that remain your asset. Weather industry volatility with financial buffers you control. Access institutional reinsurance markets for catastrophic events while retaining profits.
The Data Don't Lie
3-5x
higher premiums than comparable industries – if you can find coverage at all.
Source: Milliman Cannabis Insurance Analysis
61%
of cannabis operators report insurance availability as a top-3 business challenge.
Source: Cannabis Business Times 2024 Industry Survey
$1.2B+
in estimated uninsured losses annually across the industry due to coverage limitations.
Source: Milliman Market Research
For Operations Ready to Break Through
Captive insurance structures work best for licensed businesses with established operations and growth trajectories:
- Consistent or increasing revenue streams supporting premium funding
- Multi-location or vertically integrated operations with complex risk profiles
- Strong compliance and quality control protocols already in place
- Strategic vision requiring stable, long-term insurance solutions
Prime candidates include:
Multi-state dispensary groups | Licensed cultivation & processing operations | Manufacturing & extraction facilities | Testing & compliance laboratories | Cannabis tech & supply chain platforms | Ancillary product manufacturers & distributors
Not every operation is ready for a captive, and that's okay. We'll help you determine if the timing and scale align with this strategy. If it won’t work for your company, we will tell you before you ever spend a dime.
From Seed to Harvest
Your Captive Formation Journey
Germination: Risk Assessment
We analyze your current coverage, identify exposures, and calculate total cost of risk across all operations.
Growth Stage: Feasibility Analysis
We model financial structure, determine optimal domicile, project multi-year performance scenarios, and assess your operational readiness.
Flowering: Captive Formation
We handle regulatory filing, entity formation, governance structure, and full compliance framework establishment. “We keep you legal.”
Harvest & Maintenance: Ongoing Management
We provide continuous administration, claims management, financial reporting, and strategic optimization as your operation evolves.

Clearing the Air: Common Questions
Captive insurance companies are regulated by state insurance departments and operate within established insurance legal frameworks. The captive insures risks related to licensed, state-legal operations. 3F works exclusively with properly licensed businesses operating in full compliance with applicable state and local regulations.
While every situation is unique, captives typically become financially viable for cannabis operations with annual revenues exceeding $5-10M and/or annual insurance costs of $250K+. We'll provide a detailed feasibility analysis specific to your operation during consultation.
Captives are typically structured as 5-10 year strategies. Initial years focus on building reserves and establishing the structure, with potential underwriting profits and investment income accruing over time. Your specific timeline depends on loss experience, premium volume, and market conditions.
Typically 4-6 months from initial assessment to captive activation, depending on domicile selection and regulatory processing timelines.
Stop Watching Profits Go Up in Smoke
The cannabis industry has always required innovative thinking to break through systemic barriers. Your insurance strategy should be just as forward-thinking as your operation.
Discover whether a captive insurance solution can transform your risk management from cost burden into competitive advantage – and put real money back into your business.
Download the Infographic: Rooted in Strategy: The Captive Insurance Advantage for Cannabis Businesses