
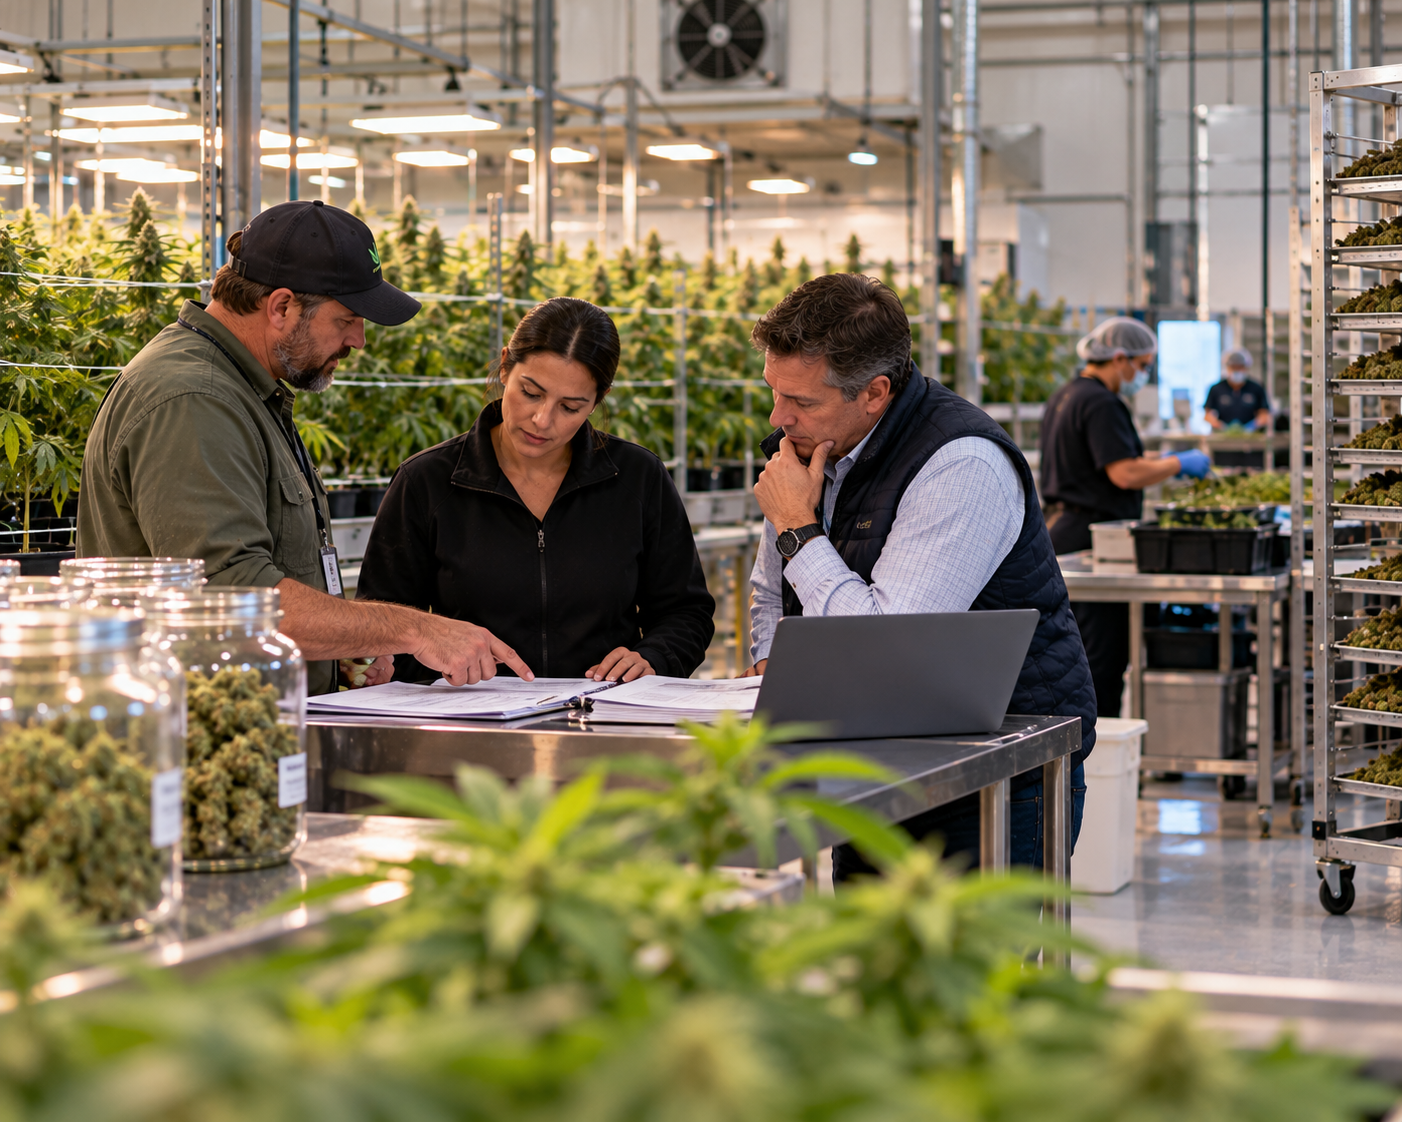
A group captive makes sense for cannabis operators who share similar risk profiles and coverage needs but whose individual premium spend does not yet support a single-parent captive structure on its own. Cannabis is one of the strongest industries for this model precisely because the commercial insurance market is so thin — operators across cultivation, processing, retail, and distribution face the same coverage gaps, the same product liability exposures, and the same absence of standard market solutions. A group captive lets them address those shared needs collectively, lower the entry threshold for each member, share administrative costs, and begin building equity in a structure they own — rather than continuing to pay commercial premiums that generate no return.
How a Group Captive Works and Why Cannabis Is a Strong Fit
In a group captive, multiple unrelated companies come together in a shared captive structure — each contributing premiums, sharing in the risk pool, and participating in the financial results. Administrative and management costs are spread across the membership rather than borne by a single operator. Coverage terms are negotiated collectively and designed around the actual exposure profile of the group rather than constrained to what a commercial carrier will write. Each member’s premium dollars remain within the captive structure rather than leaving to a commercial carrier — meaning that underwriting profit, when losses stay below premiums, stays in the captive and ultimately benefits the members.
Cannabis is a particularly natural fit for the group captive model for several reasons. First, the coverage needs are remarkably consistent across operators: product liability, contamination and recall exposure, regulatory defense, property coverage for inventory and grow operations, and general liability are common requirements regardless of whether an operator is a cultivator, a processor, a dispensary, or a distributor. Second, the commercial market’s failures are equally consistent — every cannabis operator faces the same exclusions, the same pricing premium, and the same gaps. A group captive designed specifically for cannabis operators can address those shared exposures with a collective underwriting approach and actuarial data that improves over time as the group accumulates its own loss history.
Third, the entry threshold for a single-parent captive — while lower in cannabis than in most industries precisely because commercial coverage is so scarce — is still a consideration. A group captive structure can bring operators into a captive arrangement at a meaningfully lower individual premium level, making the structure accessible to a broader range of cannabis businesses. As an operator’s premium spend grows over time, a well-structured group captive can include protected cell arrangements that progressively segregate each member’s own performance, preserving the group’s collective benefits while rewarding individual operators whose loss experience is strong.
The forward-looking 280E dimension applies to the group captive exactly as it does to the single-parent structure. When 280E is withdrawn — whether through rescheduling or federal legislative action — operators already participating in a group captive will capture the full tax benefits immediately, with reserves accumulated and equity already building. Members who join early position themselves ahead of competitors who wait for the regulatory environment to clarify before acting. A group captive also builds collective actuarial data about cannabis-specific loss patterns that has real value as the industry matures and the commercial market eventually develops more interest in the space.
Member selection matters significantly in a group captive. The structure works best when members share similar operational characteristics, risk management approaches, and compliance cultures — because the group’s loss experience affects all members. Well-run group captives maintain underwriting standards for membership and remove or restrict members whose performance consistently degrades the group’s results. These tasks and responsibilities are managed by the captive manager, who oversees both the technical operation of the captive and the ongoing evaluation of member performance.
Key Points
• Lower individual entry threshold: A group captive allows cannabis operators to access captive insurance at a lower individual premium level than a single-parent structure requires. Administrative and management costs are shared across members, making the economics work at smaller individual scales.
• Shared coverage for shared gaps: Cannabis operators across segments face the same commercial market failures. A group captive designed around cannabis-specific exposures — product liability, contamination, regulatory defense, inventory coverage — addresses those shared needs more efficiently than each operator attempting to address them individually.
• Member selection is critical: A group captive pools risk among its members. Strong underwriting standards for admission and ongoing performance monitoring protect well-run operators from subsidizing those with weaker risk management. Protected cell arrangements can further segregate individual member performance within the group structure.
• 280E forward-looking advantage: Group captive members who are already established when 280E is withdrawn will capture the full tax benefits immediately. Early participants build equity and reserves that later entrants will have to develop from scratch.
• Three streams of financial return: Underwriting profit when group losses stay below premiums, investment income earned on reserves held in the captive, and compounding equity over time — shared among members rather than surrendered to a commercial carrier.
What is the difference between a group captive and a single-parent captive?
A single-parent captive is owned and controlled by one company, which insures only its own risks. All underwriting profit, investment income, and equity belong entirely to that one owner. A group captive is owned collectively by multiple unrelated companies, which pool their risks and share in the financial results. The group structure lowers the individual entry threshold and spreads administrative costs, but also means that each member’s financial outcome is influenced by the loss experience of the group as a whole. For cannabis operators with sufficient individual premium spend, a single-parent captive offers the greatest financial control. For operators who are not yet at that threshold, a group captive provides access to the same structural benefits at a lower individual scale.
What risks can a cannabis group captive cover?
A cannabis group captive can be structured to cover the specific exposures that the commercial market routinely excludes or prices prohibitively: product liability for contamination, mislabeling, and adverse reactions; recall and contamination expense; general liability; property coverage for inventory and grow operations; regulatory defense costs; and other operational risks unique to the cannabis industry. Because the captive is designed around its members’ actual risk profiles, coverage terms can address the real gaps rather than being constrained to products a commercial carrier will write at scale.
How are group captive members selected?
Group captive membership is typically subject to underwriting review, which evaluates the prospective member’s risk profile, loss history, compliance practices, and operational characteristics. The goal is to assemble a group of members with similar exposures and compatible risk management cultures — because the group’s collective loss experience affects every member’s financial outcome. For cannabis group captives, operational segment (cultivation, processing, retail, distribution) and state regulatory environment are relevant factors in member compatibility. The captive manager oversees both the admission process and ongoing performance monitoring.
When does a single-parent captive make more sense than a group captive for a cannabis operator?
A single-parent captive is the stronger choice when an operator has sufficient individual premium spend to support the structure economically on its own. In a single-parent captive, all underwriting profit, investment income, and equity belong entirely to the owner — there is no pooling with other members, no shared loss exposure, and no dependency on the performance of other operators. The group captive is the right starting point for operators who are not yet at that individual threshold but want access to the same structural benefits, coverage flexibility, and financial returns. A feasibility study is the appropriate first step to determine which structure fits a specific operator’s situation.
Common Misconceptions
“A group captive is just another insurance pool — same as what we have now.”
A group captive and a commercial insurance pool are fundamentally different structures. In a commercial pool, premiums leave the policyholder entirely — underwriting profit, investment income, and equity all belong to the carrier. In a group captive, members own the structure, coverage terms are designed around actual member exposures rather than commercial appetite, and the financial results — underwriting profit and investment returns — benefit the members rather than an external carrier. The group captive is a licensed insurance company owned by its members, not a purchasing arrangement.
“If another group member has bad losses, it will sink our captive.”
Member selection and structure design address this directly. Well-run group captives maintain underwriting standards and remove members whose performance is consistently poor. Protected cell arrangements within a group captive can segregate each member’s loss experience so that individual performance is ring-fenced rather than fully pooled — preserving the group’s collective benefits while limiting cross-member exposure. The captive manager’s role includes monitoring member performance and maintaining the integrity of the group’s risk pool.
“280E makes a group captive not worth considering right now.”
280E limits the deductibility of premiums but does not eliminate the operational and coverage benefits of a group captive structure. And the forward-looking case is compelling: when 280E is withdrawn, members already established in a group captive will capture the full tax benefits from day one — with reserves accumulated and equity already building. Operators who wait will start from scratch at the exact moment the advantage becomes most valuable. For cannabis operators whose individual premium spend does not yet support a single-parent captive, a group captive is the right structure to enter now rather than waiting for the commercial market to improve or the regulatory environment to resolve.
Quick Summary
• A group captive makes sense for cannabis operators who share similar risk profiles and coverage needs but whose individual premium spend does not yet support a single-parent structure. It lowers the entry threshold while providing access to the same structural benefits.
• Cannabis is a natural fit for the group captive model because operators across segments face the same commercial market failures — the same exclusions, the same pricing premium, the same coverage gaps. Shared exposure means shared solutions.
• Member selection and structure design protect well-run operators. Strong underwriting standards, ongoing performance monitoring, and protected cell arrangements prevent weaker members from degrading the group’s financial results.
• Operators who join a group captive now will be positioned to capture the full tax benefits when 280E is withdrawn — with reserves and equity already accumulated. Those who wait will be starting from scratch at the moment the advantage is greatest.
Discover Tailored Insurance Solutions
Unlock the potential of customized captive insurance designed specifically for your unique business needs.