
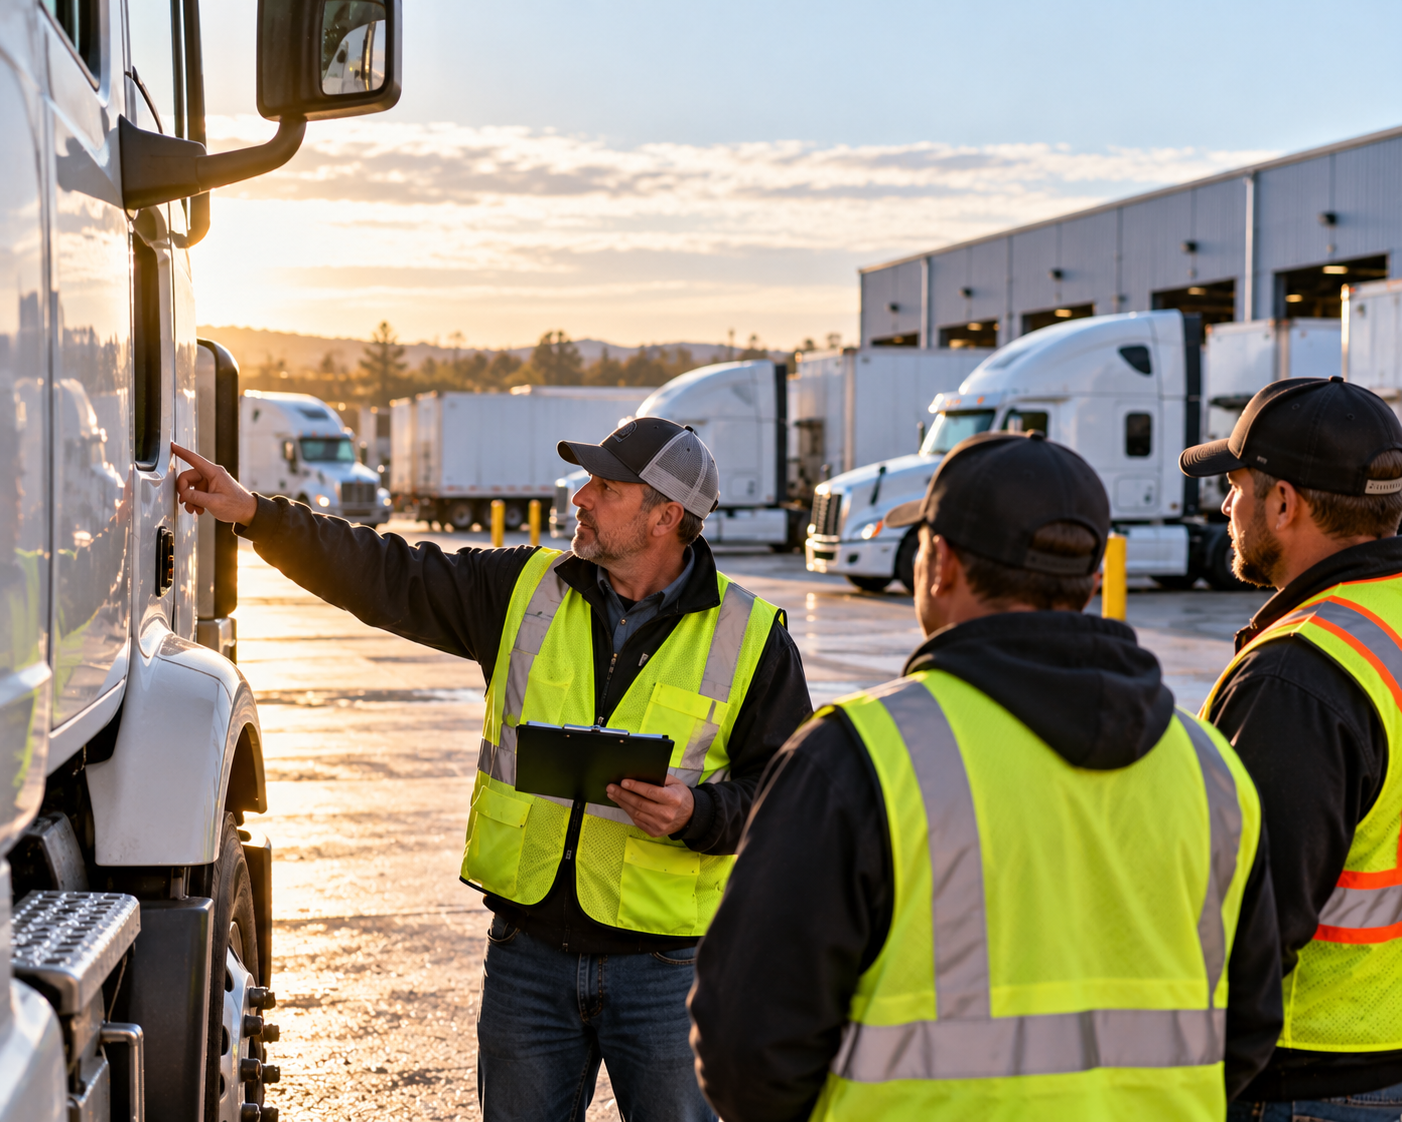
In a commercial insurance pool, a transportation company’s safety record gets averaged in with every other operator the carrier writes — the disciplined and the undisciplined alike. A carrier with an outstanding safety program receives some credit at renewal, but the underwriting profit generated by their low loss experience flows to the commercial carrier, not back to them. A captive breaks that arrangement entirely. When a transportation company insures through a captive, the financial benefit of every prevented accident, every clean inspection, and every low-loss quarter belongs directly to the operator.
Why Safety Performance Has a Direct Dollar Value in a Captive
Commercial insurance is a pooling mechanism. Carriers spread risk across large groups of policyholders, smooth out individual loss experience, and retain the underwriting profit — the difference between premiums collected and claims paid. A carrier with strong safety performance contributes to that pool’s profitability but cannot extract the value their discipline created. Their premiums are partly supporting losses generated by operators with weaker safety cultures. The benefit of their investment in training, technology, and compliance is diluted across the entire pool.
A captive operates on the opposite principle. The operator funds their own risk layer through premium payments to a licensed insurance company they own. When losses stay below those premiums — because drivers are trained, vehicles are maintained, hours-of-service rules are followed, and compliance scores are strong — the underwriting profit accumulates in the captive and belongs entirely to the operator. There is no pooling to dilute it. The financial reward for a prevented accident is felt immediately and in full, exactly as the cost of a preventable loss would be.
Safety technology amplifies this dynamic significantly. Telematics systems that monitor speed, braking, and hours of service generate data that reduces both loss frequency and severity. Forward-facing dashcams provide exculpatory evidence that defeats fraudulent claims and reduces settlement costs. Driver coaching programs supported by telematics data measurably reduce accident rates over time. In a commercial program, the financial return on these investments is indirect and partial — at best a modest premium credit shared with the carrier. In a captive, every claim prevented by that technology flows directly to the operator’s bottom line.
The financial structure of a captive builds wealth in three ways simultaneously. First, underwriting profit: premiums paid in exceed claims paid out, and the difference belongs to the operator. Second, investment income: reserves held in the captive before claims are paid are invested and earn returns year after year — the same way commercial carriers have quietly profited from policyholder premiums for decades. Third, compounding equity: the captive’s net worth grows over time as underwriting profit and investment income accumulate. A transportation company with a strong safety program and a well-run captive is not just controlling insurance costs — it is building a genuine financial asset. These tasks and responsibilities are typically managed by the captive manager in coordination with the operator.
Key Points
• The commercial pool dilutes both losses and gains: In a commercial program, a carrier with strong safety performance subsidizes weaker operators and surrenders the underwriting profit their discipline created. A captive prices risk entirely on the operator’s own experience — meaning the benefit of good safety performance is captured in full.
• Every prevented loss has a direct dollar value: In a captive, the financial benefit of a prevented accident, a clean roadside inspection, or a driver coaching intervention that avoids a claim stays with the operator rather than benefiting the commercial pool.
• Safety technology has measurable captive ROI: Telematics, dashcams, driver coaching, and maintenance programs all reduce loss frequency and severity. In a captive, the financial return on that technology investment is direct — every claim those tools prevent flows back to the operator as underwriting profit.
• Three streams of financial return: Underwriting profit when losses are low, investment income earned on reserves held before claims are paid, and compounding equity over time. A well-run captive turns a transportation company’s safety culture into a growing financial asset.
• CSA scores drive the financial outcome: Strong CSA scores reduce accident probability, reduce verdict severity when accidents do occur, and maximize underwriting profit in a captive structure. The same compliance discipline that protects against nuclear verdicts also generates the most favorable financial outcome for the captive owner.
How does a captive reward transportation companies with strong safety programs?
In a captive, premiums are paid into an insurance company the operator owns. When losses stay below those premiums — because of strong safety performance — the underwriting profit belongs to the operator, not a commercial carrier. There is no pooling to dilute the reward. A carrier that prevents accidents through training, compliance, and technology investment captures the full financial value of that performance rather than sharing it with the market.
What safety technologies help reduce insurance costs in a captive?
Telematics platforms that monitor speed, hard braking, and hours of service reduce loss frequency by identifying risky driving behaviors before they result in accidents. Forward-facing dashcams reduce settlement costs by providing exculpatory evidence against fraudulent or inflated claims. Driver coaching programs supported by telematics data have demonstrated measurable reductions in accident rates. Preventive maintenance programs reduce mechanical failure claims. In a captive, each of these tools has a direct and calculable return: every claim prevented stays as underwriting profit in the operator’s captive.
Can a transportation company’s safety record actually generate profit?
Yes — in a captive. Commercial insurance generates no profit for the policyholder regardless of safety performance; premiums leave the business and do not return unless a claim is paid. In a captive, the structure is reversed: premiums stay within an entity the operator owns, are invested and earn returns, and generate underwriting profit whenever losses stay below the premium level. A transportation company with a disciplined safety culture and a well-run captive is not just managing insurance cost — it is generating a financial return from its safety investment.
How do telematics and dashcams affect captive insurance outcomes?
Telematics data reduces accident frequency by enabling proactive driver coaching, and dashcam footage reduces claim severity by providing objective evidence that defeats inflated or fraudulent claims. In a commercial program, both effects generate modest premium credits that are shared between the operator and the carrier’s book of business. In a captive, both effects translate directly into underwriting profit for the operator. The ROI on safety technology is fundamentally different in a captive environment — and operators with these tools already in place are often the best candidates for a captive structure.
Common Misconceptions
“We already have a good safety program — we’re getting full value from it through our commercial rates.”
A strong safety record earns some commercial premium credit, but the underwriting profit generated by low losses still flows entirely to the commercial carrier. Every dollar saved by a prevented accident is pooled across the market — the operator captures a fraction of the benefit their safety culture created. In a captive, that same safety discipline generates underwriting profit that belongs entirely to the operator, every year, compounding over time. The difference between partial commercial credit and full captive ownership of that underwriting profit is substantial.
“Safety programs are a cost center, not a profit driver.”
In a commercial insurance program, that framing has some truth — safety investment reduces premiums indirectly and at the margin, but it generates no direct return. In a captive, the math changes. Every claim prevented by a driver coaching program, a dashcam system, or a maintenance protocol is a direct addition to underwriting profit. Safety investment has a calculable, compounding financial return in a captive structure that simply does not exist in a commercial program.
“Our commercial carrier already prices us on our own loss history.”
Commercial carriers use loss history as one factor among many, applied within rate structures that reflect the broader book of business. Even experience-rated programs pool and smooth individual performance. A captive prices entirely on the operator’s own experience — no pooling, no smoothing, no sharing the benefit with the market. A consistently low-loss carrier in a captive captures the maximum financial return from their performance. A consistently low-loss carrier in a commercial program captures a fraction of it.
Quick Summary
• In a commercial insurance pool, a transportation company’s safety performance is diluted — the underwriting profit it generates flows to the carrier and subsidizes less disciplined operators. In a captive, that profit belongs entirely to the operator.
• Every prevented accident, clean inspection, and safety technology intervention that avoids a claim is a direct financial return in a captive structure — not an indirect premium credit shared with the market.
• Underwriting profit when losses are low, investment income earned on reserves, and compounding equity over time — a captive turns a transportation company’s safety culture into a growing financial asset rather than a cost of doing business.
• Carriers generating approximately $300,000 or more in annual premium spend with strong safety programs and low loss histories are among the most compelling captive candidates — because the gap between what they’re paying and what they’re getting is largest.
Discover Tailored Insurance Solutions
Unlock the potential of customized captive insurance designed specifically for your unique business needs.