
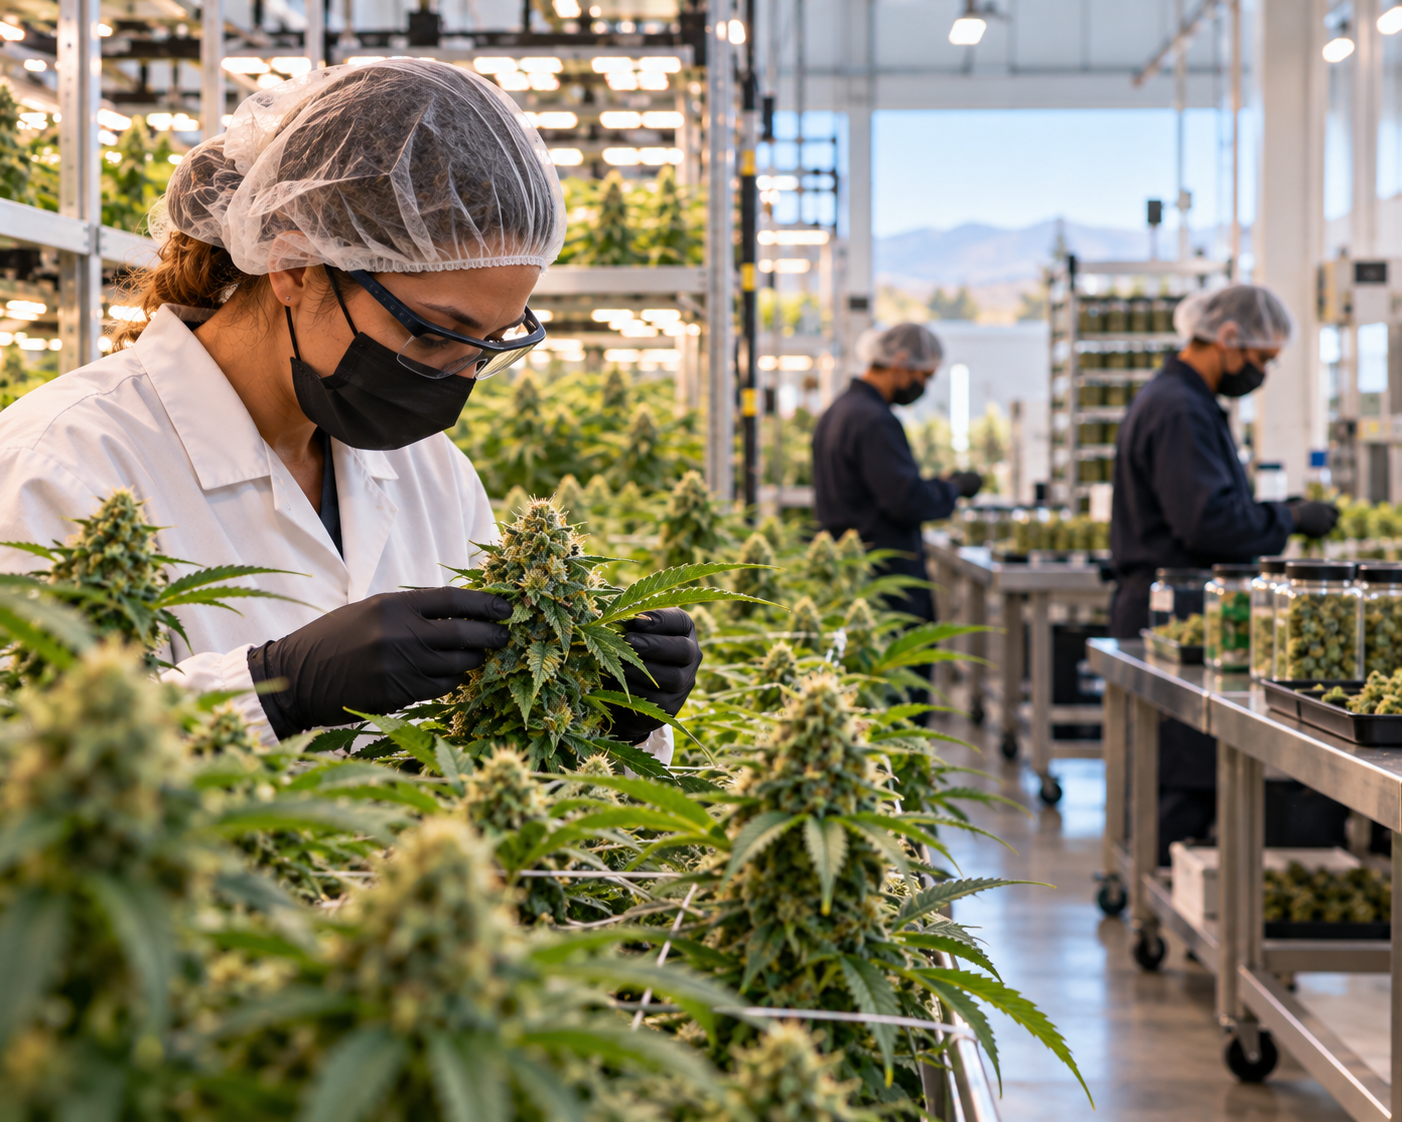
Cannabis companies increase stability through disciplined risk management, strong compliance programs, and strategic insurance structures — with captive insurance being one of the most powerful tools available. A captive allows cannabis operators to formalize their already-substantial self-insured risks in a legitimate, tax-efficient structure, gain coverage stability independent of a volatile commercial market, and build a genuine financial asset that grows alongside the operation.
Why Stability Is a Unique Challenge for Cannabis Operators
The cannabis industry faces a uniquely volatile operating environment. Federal illegality limits access to traditional banking, capital markets, and commercial insurance. The carriers willing to write cannabis risks are few, their terms are restrictive, and their presence in the market is inconsistent — entering and exiting as their own appetite shifts. Cannabis operators who depend entirely on the commercial market for their risk management are building on an unstable foundation.
Most cannabis companies are already self-insuring significant portions of their risk — not by choice, but by necessity. Crop losses, equipment failures, product contamination, theft, and business interruption gaps are all costs that operators absorb informally when commercial coverage isn’t available or affordable. The question isn’t whether to carry that risk; it’s whether it is being managed as efficiently as possible. A captive formalizes all of that retained exposure in a single, legitimate, licensed insurance company with actuary-priced policies — providing coverage stability that the commercial market simply cannot offer.
Beyond coverage stability, a well-run captive is a genuine financial asset built through three streams: underwriting profit when losses stay below premiums, investment income earned on reserves — the same way commercial carriers quietly profit from policyholder premiums year after year — and compounding equity that belongs entirely to the operator. A well-designed captive is not a tax scheme — it is a licensed, regulated insurance company whose advantages flow from the integrity of the structure.
There is also a compelling forward-looking argument for acting now. Currently, IRC Section 280E limits the deductibility of ordinary business expenses for cannabis operators, including insurance premiums, because cannabis remains a Schedule I controlled substance federally. If and when 280E is withdrawn — whether through rescheduling or federal legislative action — the full tax benefits of captive ownership become immediately available. Operators who have already built and funded a captive will capture those benefits from day one. Those who waited will be starting from scratch, years behind on equity accumulation and reserve building. The captive set up today under current law is the same captive that becomes significantly more powerful the moment the regulatory environment shifts.
Key Points
• Why commercial insurance is unstable for cannabis: Limited carrier appetite, inconsistent market availability, restrictive terms, and high premiums reflect the commercial market’s discomfort with a federally complex industry — leaving operators exposed to sudden coverage gaps at renewal.
• What cannabis companies already self-insure: Crop losses above commercial sublimits, equipment breakdown, product contamination and recall, theft of cash and inventory, workers’ compensation on cultivation operations, and business interruption gaps.
• How a captive increases stability: A captive provides consistent, predictable coverage priced on the operator’s own loss experience — independent of whether commercial carriers are willing to write the risk in any given year.
• The asset dimension: Premiums are invested and earn returns; underwriting profit stays with the operator; equity compounds over time — building financial stability alongside operational stability.
• Which structure is right: Single-parent, protected cell, and group captives are all options. Because the commercial market offers so little to cannabis operators, the feasibility conversation can begin at a lower premium threshold than in most other industries — the right structure is determined through analysis.
Why is commercial insurance so difficult for cannabis companies to obtain?
Federal illegality creates compliance risk for insurance carriers, limiting the pool willing to write cannabis risks. Those that do often charge significant premiums for relatively narrow coverage, and their appetite can shift quickly — leaving operators scrambling for alternatives at renewal. A captive eliminates that dependency entirely.
What risks do cannabis companies most commonly self-insure?
Crop losses above commercial sublimits, equipment breakdown, product contamination and recall, theft of cash and inventory, workers’ compensation gaps on cultivation operations, and business interruption are among the most common exposures cannabis operators absorb out of pocket — often with no formal structure and none of the financial benefits a captive provides.
Can a captive cover cannabis crop losses?
Yes. A captive can be structured to cover crop losses that fall outside or above commercial programs, priced by actuaries based on the operator’s own cultivation history and risk profile. This provides consistent, year-over-year protection that doesn’t disappear when a commercial carrier exits the cannabis market.
How does captive insurance interact with cannabis tax planning?
Cannabis operators face significant tax complexity under IRC Section 280E, which currently restricts ordinary business deductions for cannabis businesses. A properly structured captive — as a legitimate, licensed insurance company — provides a compliant framework for tax-advantaged reserve building, and should always be implemented with qualified legal and tax counsel. More importantly, if and when 280E is withdrawn through rescheduling or federal legislative action, full premium deductibility becomes available immediately to operators who already have a captive in place. The operators who set up now will be positioned to capture those benefits from day one — with years of compounding equity already behind them.
Common Misconceptions
“We can’t get a captive because we can’t get regular insurance.”
A captive is an alternative to the commercial market, not dependent on it. The commercial market’s reluctance to write cannabis risks is precisely why a captive is so valuable — it provides consistent, stable coverage regardless of carrier appetite, and is priced on the operator’s own experience rather than market assumptions.
“A captive is just a tax strategy for a tough industry.”
A well-designed captive is a legitimate, licensed insurance company with actuary-priced policies, proper reserves, annual audits, and full regulatory oversight. The tax advantages flow naturally from building the structure correctly — they are a byproduct of legitimacy, not the purpose of the arrangement. Cannabis operators who approach captives primarily as tax vehicles are taking on significant IRS risk.
“We’re too small or too early-stage for a captive.”
Because commercial insurance options are so limited for cannabis operators, the feasibility conversation can begin at a lower premium threshold than in most industries. Stage of business matters less than risk profile and the scope of uninsured exposure. Group captives and protected cell structures make participation accessible for operators who cannot support a standalone captive, and the feasibility process determines the right fit.
Quick Summary
• Cannabis companies already self-insure substantial risk by necessity — a captive formalizes that retained exposure in a legitimate, licensed insurance company with actuary-priced policies, independent of the volatile commercial market.
• A captive provides stable coverage for crop losses, equipment, product contamination, theft, and other risks that are either unavailable or too expensive in the traditional market.
• Premiums are invested and earn returns, underwriting profit stays with the operator, and equity compounds over time — building financial stability alongside operational stability.
• Operators who establish a captive now will be positioned to capture the full tax benefits the moment 280E is withdrawn — with equity already built, reserves already invested, and years of compounding value already working in their favor.
Discover Tailored Insurance Solutions
Unlock the potential of customized captive insurance designed specifically for your unique business needs.